NEWS FROM SUMMERLIN BENEFITS CONSULTING
U.S. bonds are coming off their worst year in almost a half-century of record-keeping, but the question is, do they look poised for a better performance in 2023?
Baby Boomers continue to face the decision to either retire or keep working for a while longer. We help mature employees prepare for their retirement future.
A little planning before you move the assets can save you a lot of pain later on. Many people move the money first and ask questions after, costing quite a bit in taxes and lost gains.
We can help you plan for managing the financial aspects of long-term care, to help ensure good quality care for the senior in your life.
Life insurance can be an important part of your financial plans. After you have decided which kind of life insurance is best for you, it's always good to compare similar policies from different...
Here’s a puzzler for you. What are the odds that you’ll be better off over the next 10 years if you hold your retirement portfolio in boring Treasury bills, money-market funds or certificates of...
Life insurance isn't just about providing financial security for your loved ones; it can also be a strategic tool for building wealth and planning for the future. One option that stands out, especially for younger adults, is Fixed Indexed Universal Life (FIUL) Insurance. But what makes FIUL a compelling choice for those in their thirties and forties? Let’s explore!
Starting a Fixed Index Annuity in your 40s lets you take advantage of stock market performance to help your asset grow for many years before you get ready to retire.
When you think of "retirement planning", you probably don’t associate this topic with someone in their twenties. But saving for retirement is becoming more and more important to the younger generations for many reasons.
Learn how to create dependable retirement income by coordinating Social Security, pensions, savings and annuities to cover your expenses and close income gaps.
Learn how life insurance evolves from income protection to legacy planning, how cash value adds flexibility, and when to review coverage for retirement.
Published: September 15, 2026 For many Americans nearing retirement, Florida continues to top the list of places to call home. Warm weather, beautiful coastlines, and an active retirement lifestyle are certainly appealing—but one of the biggest reasons people consider relocating is taxes. If you're wondering whether moving to Florida could make financial sense in retirement, it's important to understand both the advantages and the tradeoffs. While taxes shouldn't be the only factor in your decision, they can have a meaningful impact on your retirement income and long-term confidence. Here's what you should know before making a move.
A comfortable retirement is a lifelong goal for people of almost any age, in any profession, and from every state. But that isn’t to say retirement has equal value across state lines. Taxes, cost...
With U.S. stock indexes down and the Federal Reserve’s latest announcement of increases, retirees should be saving all they can but retirees' savings is also at risk.
By following the tips outlined here, impending retirees can stay on track with their plans, retire with more confidence and reduce the effect of a down market on their retirement portfolio.
A conservative, fixed-income investment strategy may result in slow and steady growth rates will prevent you from experiencing the losses that put you far behind inflation.
Published: September 15, 2026 Retirement isn't about reaching a magic number—it's about creating a lifestyle you can enjoy with confidence. One of the most common questions we hear at Summerlin Benefits Consulting is: “How much money do I really need to retire in Florida?” The honest answer is... it depends. Where you live, how you want to spend your retirement, your healthcare needs, housing costs, and your retirement income sources all play a role. Someone retiring in Miami will likely need a much different budget than someone living in Yulee or Fernandina Beach. The good news? With a little planning, you can build a retirement strategy that’s designed around your life—not someone else’s.
Cash on hand allows retirees the opportunity to avoid tapping into their portfolios during market volatility. Fixed Index Annuities can provide access to cash.
It is no secret that there is a retirement crisis facing American s . In a recent survey conducted on behalf of home financing and real estate website “Anytime Estimate,” A mericans were...
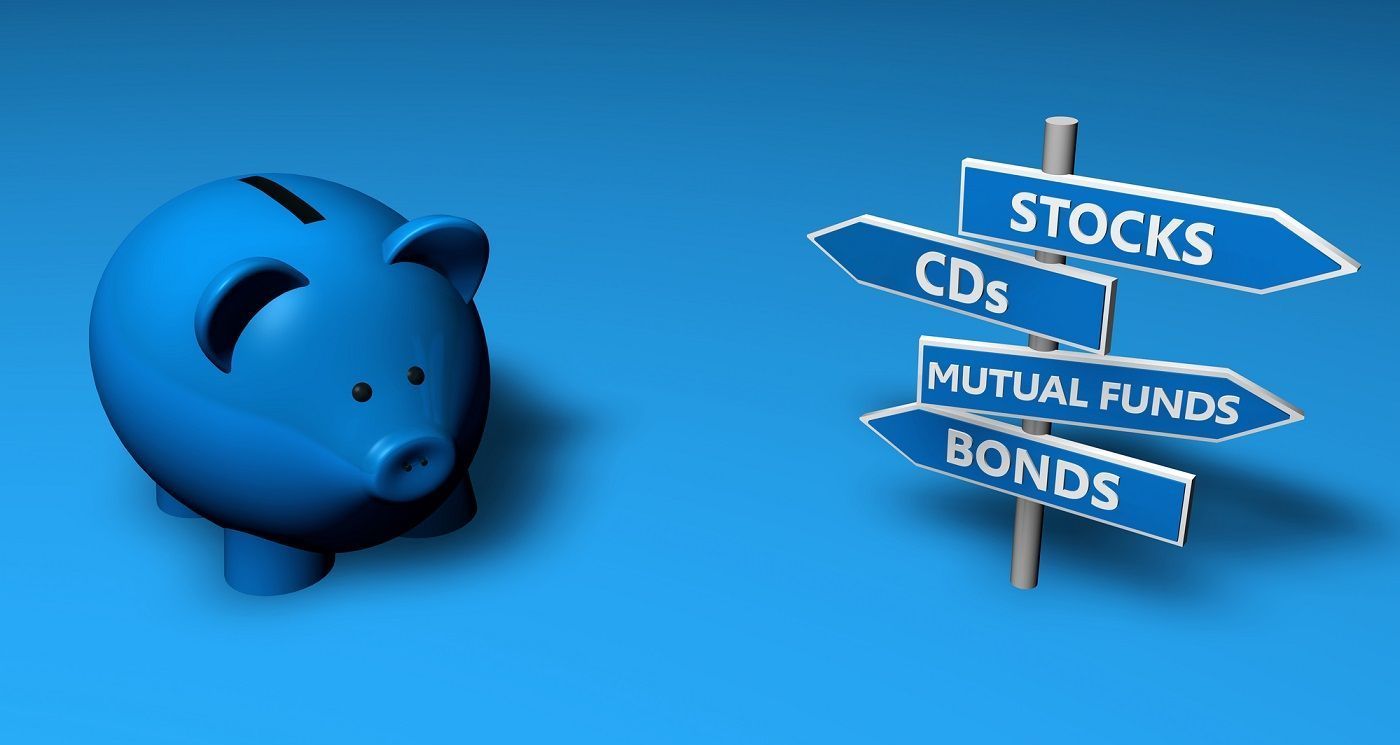
Most people think bonds are safe, but in today’s volatile climate, they are not. Interest rates are poised to rise even further, which is bad news for bonds. Investors seeking a measure of safety...
Learn how a fixed index annuity works, including index-linked interest, principal protection, surrender periods, income riders, taxes, and beneficiaries.
Learn how Fixed Index Universal Life Insurance works, its death benefit, cash value, index-linked interest crediting, costs, taxation, and risks."
Learn how annuities work, the major types, income options, guarantees, surrender periods, taxes, beneficiaries, benefits and tradeoffs before deciding.
According to a recent publication by SHRM, there were several recent employee surveys conducted which show that retirement confidence is down, with fewer workplace savers seeing themselves on track...
After contributing to Social Security for all of your working life, you might think that you should claim your benefit at 62 to get as much money out of the system as possible.
For many Americans approaching retirement, the plan sounds surprisingly simple: “I’ll work as long as I can, and then I’ll live on Social Security.” There’s nothing unusual about counting on Social Security. After years of paying into the system, it can provide an important foundation of monthly retirement income. But there is an important distinction between receiving Social Security benefits and having a retirement income strategy. Social Security was not designed to replace all of a worker’s pre-retirement income. That means people approaching retirement may want to look beyond the question of when to claim Social Security and consider a bigger question: Will my expected income be enough to support the retirement I want?
Published: July 1, 2026 After years of working hard and saving for retirement, the focus naturally shifts from building wealth to making it last. One of the most overlooked parts of retirement planning isn't just how much you've saved—it's how you withdraw those savings. A thoughtful, tax-efficient withdrawal strategy can help reduce unnecessary taxes, extend the life of your retirement assets, and give you greater confidence throughout retirement. At Summerlin Benefits Consulting, we believe retirement planning isn't just about growing your savings—it's about helping you protect what you've worked so hard to build through thoughtful, personalized planning.
What's New for 2026: Traditional and Roth IRA Limits
If you’re feeling generous and planning to share your wealth with family or friends, you might be wondering whether the IRS is going to come knocking. The good news? Most people can give freely without owing a dime in gift taxes — but there are limits you should be aware of. Let’s break down how the gift tax works and what the exclusion amounts are for 2025.
The Tax Cuts and Jobs Act of 2017 (TCJA) made many changes to U.S. tax law. However, some of those changes included sunset provisions that will cause them to expire at the stroke of midnight on January 1, 2026, unless Congress acts to extend them. For today’s retirees, these changes will have significant impact. The three key components of the TCJA that will impact retirees in 2026 are going to be the changes pertaining to income-tax, estate taxes, and gift taxing.
Every crisis is an opportunity. The massive turmoil on financial markets so far this year is no exception. Here are three things that every middle-class American can do with their 401(k), IRA or...
Women often experience some very specific retirement risks that could jeopardize their lifetime income. It’s time to spill the tea, on what today’s woman is facing in retirement and how best to...
Originally published: April 24, 2026 Updated: June 24, 2026 If you’re planning for retirement, you’ve probably heard about 401(k)s, Roth IRAs, and traditional savings accounts. But there’s a powerful strategy that often flies under the radar: Fixed Indexed Universal Life insurance (FIUL). When structured correctly, an FIUL can offer a three-part tax advantage that’s hard to find anywhere else, and it could make a meaningful difference in how much of your money you actually keep. What Makes FIUL Different? FIUL is a type of permanent life insurance that builds cash value over time. That cash value is linked to a market index (like the S&P 500), which means your savings have the potential to grow, but with a floor that protects you from market losses. On top of that, a properly structured FIUL comes with three distinct tax benefits that work together. The Triple Tax Advantage Tax-Deferred Growth — Your cash value grows inside the policy without triggering annual taxes. No tax bill each year; your money compounds without the drag. Tax-Free Retirement Income — You can access your cash value in retirement through policy loans. Because it’s a loan, not a withdrawal, it’s generally not treated as taxable income. Tax-Free Death Benefit — When you pass away, your beneficiaries receive the death benefit income-tax-free. Unlike inherited 401(k) balances, there’s no ordinary income tax owed. Tax-Deferred Growth: Let Your Money Work Harder Inside an FIUL, your cash value earns index-linked credits without generating a taxable event each year. That means no annual capital gains tax, no income tax on interest, nothing. The growth remains in the policy and keeps compounding. Over a 20–30 year accumulation period, that tax deferral creates a real, measurable difference. Every dollar that would have gone to taxes instead stays invested and keeps growing on your behalf. Tax-Free Income in Retirement: The Policy Loan Strategy Here’s where FIUL really shines as a retirement planning tool. Rather than making withdrawals from your cash value (which could be taxable), you can borrow against it. A policy loan isn’t considered a distribution by the IRS, so there’s no taxable event and no required repayment schedule. Traditional retirement accounts like a 401(k) require you to pay ordinary income tax on every dollar you withdraw. With a properly structured FIUL, your retirement income can come out tax-free, which is especially valuable if you expect to be in a higher tax bracket later in life. The key phrase is “properly structured.” If a policy is overfunded past a certain IRS threshold — known as the Modified Endowment Contract (MEC) rule, or the “7-pay test” — it loses this tax-free loan treatment. This is why working with an experienced advisor matters. Getting the structure right from day one is what makes the strategy work. Is FIUL Right for You? An FIUL tends to be a strong fit for people who have already taken advantage of their 401(k) employer match and want additional tax-advantaged savings. It’s especially useful for those who expect tax rates to rise in the future, or who want a retirement income stream that won’t push them into a higher bracket. It’s a long-term strategy, typically most effective over 20 or more years of consistent funding, but as part of a well-rounded retirement plan, it can fill gaps that other accounts simply can’t. A properly structured FIUL lets your money grow tax-deferred, gives you tax-free income in retirement through policy loans, and passes a tax-free death benefit to your loved ones. That’s a combination you won’t find in a 401(k) alone. Ready to see how an FIUL fits your retirement plan? Learn more by joining us at one of our upcoming dinner seminars! Contact us today for our seminar schedule, or to schedule a complimentary consultation with our team at Summerlin Benefits Consulting. We're here to help you protect your money and protect your future! Note: This content is for informational purposes only and does not constitute tax or legal advice. Summerlin Benefits Consulting does not provide social security, specific advice related to taxes, or legal advice. Consult a tax/legal professional for guidance with your individual situation.
401k and IRA contribution and income limits have increased in 2023 as expected. Feel free to reach out to us for a no-obligation meeting if you are looking for guidance.
We know that many people will have more than one job during their working years and that these 401(k) accounts are often left behind after a job change. So, what can be done?
You may remember back in 2019 when Congress passed the SECURE Act to enhance various rules around retirement saving. Then along came what’s now being referred to as SECURE 2.0, or “The Securing a Strong Retirement Act”, which expanded the original act. This impacted retirement planning and wealth management even further and some retirees are struggling to keep up with these new changes to the law.
New legislation may impact future financial security. Even if you’ve covered all of the retirement planning bases, like income generation, taxes, inflation.
As a grandparent, you hold a special place in the family structure. Your wisdom, experience, and unconditional love have a profound impact on the lives of your children and grandchildren. “And how does this relate to retirement planning?”, you may ask. Well, being an involved grandparent requires time, attention, and for some- travel and financial means.
While getting an early start on retirement planning is important for both men and women alike, women tend to face some unique challenges in life that make it even more urgent. Moreover, if you're a woman who feels behind in retirement planning to begin with, the disparities can be even larger.
We are well into the new year and resolutions are in full swing. Maybe this year it’s not about eating better or getting more exercise, but instead about your financial health, which can have a profound impact on living comfortably down the road. Even if you are several years off from retiring, there’s no time like the present to take a deep dive into your retirement plan to make sure you feel confident about your future.
FIA is based on the performance of a specific market index. If it goes up, the asset grows. If the index performs poorly, the investment is protected by insurance.
We dream about retiring and imagine doing so while we’re still young enough to enjoy it. How can you set yourself up to retire and not have to go back to work?
There is no “one size fits all” answer to how much is enough when it comes to retirement. That is why retirement planning is often thought of as a complicated and taxing topic. But it doesn’t have to be. At Summerlin Benefits Consulting, we believe in making things simple for our clients. Below, we will outline some of the basic steps one should take when determining how much they will need to have in their retirement nest egg to live comfortably when they retire.
This year, we will experience record-breaking levels of Americans entering retirement. In fact, nearly 11,000 people per day are expected to turn 65 this year. Experts have begun calling this wave of retirement the “silver tsunami”, or “peak 65”.
Originally published: March 6, 2026 Updated: August 10, 2026 For many people approaching retirement, market volatility becomes a major concern. While fluctuations in the market are normal, they can have a greater impact on your finances when you are close to relying on your savings for income. After years of building your retirement nest egg, protecting those assets becomes just as important as growing them.
Have you ever received a 100-page financial plan from your advisor only to find out that less than 10 of those pages were useful? Typically, only a few pages of a financial plan will focus on strategy and investment choices; the rest usually cover fee breakdowns, risk and return explanations, and regulatory compliance disclosures. This may seem overwhelming when only a fraction of the pages are actually helpful! You’re not the only one that may be thinking, “Is this standard or should I consider finding a new advisor?”
Consider what you might be giving up. Recession fears continue to spike as major indexes are approaching bear market territory, after months of market volatility that have put a strain on...
Retiring earlier means living in retirement longer: The assets you’ve saved over your career will need to stretch farther. We can help.
A new study shows the oldest adults who retired before 2000 need more than $500 a month extra just to maintain the same level of buying power.
Retirement saving can be daunting, especially if you don’t know where to start. But luckily, there is a general guideline, called the 4% rule to help you plan.