How Do You Know You're Financially Ready to Retire?
How Do You Know You're Financially Ready to Retire?
You may be financially ready to retire when your expected income and savings can reasonably support your spending needs throughout retirement, with room for taxes, healthcare, rising prices, and unexpected expenses. The answer depends on how your resources fit the life you want to live, how long they may need to last, and how much flexibility you have when circumstances change.
Summerlin Benefits Consulting approaches retirement education with an emphasis on understanding your needs before considering insurance solutions. A useful starting point is to connect what you have saved with what you will need to spend.
What will your retirement actually cost?
Start with your own spending records. Review a full year so you capture annual insurance bills, property taxes, holiday spending, and other costs that a single month's budget may miss.
Separate your estimates into three groups:
- Essential expenses: housing, groceries, utilities, transportation, insurance, healthcare, and required debt payments.
- Flexible expenses: travel, dining out, hobbies, gifts, and other activities you could adjust if needed.
- Occasional expenses: home repairs, replacing a vehicle, helping family, or other larger purchases.
Then consider what will change. Commuting costs may fall, while travel or hobby spending may rise. A paid-off home can reduce expenses, but maintenance, insurance, and property taxes still belong in the budget.
Include the retirement you hope to enjoy. A budget that leaves out the things that matter to you can make retirement look more affordable on paper than it feels in daily life.
Where will the money come from, and when?
List your expected income sources and their starting dates. These might include Social Security, a pension, part-time work, withdrawals from savings, and payments from an existing annuity.
For each source, ask:
- When can payments begin, and what amount should I use in my estimate?
- Will the amount change over time?
- Is it paid for a set period or for life?
- What would continue for a surviving spouse?
- What taxes or deductions could affect the amount available to spend?
Use current benefit estimates and actual contract information. The Social Security Administration's retirement guidance explains why claiming age, work, health coverage, and longevity belong in this decision.
Compare income with expenses for different stages of retirement. The years between your last paycheck and the start of a pension or Social Security benefit may look different from later years.
Any amount your income does not cover is a gap that savings or other resources would need to fill. Identifying that gap helps you understand
the job your savings must do.
What changes when you begin using savings for income?
During your working years, you may add money to savings regularly. In retirement, you may begin taking money out to pay bills. That shift makes the amount and timing of withdrawals especially relevant.
If investments decline while you are withdrawing from them, you may need to sell more holdings to provide the same spending amount. The order in which gains and losses occur can therefore affect how long savings last. This is called sequence-of-returns risk.
Before retiring, consider how you would cover near-term expenses during a market decline. Would you have accessible reserves? Could you adjust optional spending? Would other income continue? Personal investment and withdrawal decisions deserve review with an appropriately qualified investment professional.
Insurance options can have a role in some retirement income situations. An annuity may provide income for a stated period or for life, depending on the contract and elections. Understand its charges, access restrictions, surrender provisions, and whether payments adjust for inflation. Guarantees depend on the issuing insurer's financial strength and claims-paying ability. An annuity is not a substitute for money you need readily available.
What does the 4% rule tell you about readiness?
The 4% rule is a withdrawal guideline drawn from historical research, not a guarantee that your savings will last. Its familiar approach starts with withdrawing 4% of an investment portfolio's initial value in the first year, then adjusting that dollar amount for inflation in later years.
It does not mean withdrawing 4% of whatever the account is worth every year. William Bengen's original research examined historical stock and bond portfolios and retirement periods of at least 30 years. Those assumptions help explain the guideline's context and limits.
Whether any withdrawal approach fits you depends on your retirement length, investment mix, market results, inflation, costs, taxes, and spending flexibility. A longer retirement or substantial expenses early on can change the picture.
Use the guideline to frame questions about withdrawals. A percentage by itself cannot determine whether you are ready to retire or what you should withdraw personally.
How much time should your resources cover?
Your retirement may last longer than you expect. Family history and health are useful considerations, but neither provides an exact end date. For couples, consider the possibility that one spouse will need income for years after the other dies.
Look beyond the first year's budget. Ask how your resources would respond to a longer retirement, higher everyday costs, or increased care needs. A fixed payment can help provide a predictable dollar amount while still buying less as prices rise.
The
Consumer Financial Protection Bureau's retirement resources also highlight the importance of considering debt, income, assets, and future financial decisions together.
Ready to Talk About Your Retirement?
No pressure. No obligation. Just a conversation about your goals and concerns.
Have you accounted for healthcare and taxes?
Healthcare needs a place in the budget before you leave work. Confirm when employer coverage ends and what coverage will replace it. Medicare eligibility usually begins at 65, although some people qualify earlier. If you retire before becoming eligible, identify coverage and its cost for the intervening years. Check Medicare's enrollment guidance for your situation.
Include premiums and out-of-pocket expenses, and consider how a future need for help at home or other care could affect spending. Confirm coverage details rather than assuming an insurance program pays every expense.
Taxes also affect the income you can spend. Account types and individual circumstances matter. The IRS explains that distributions from retirement plans and IRAs before age 59½ may involve an additional 10% tax unless an exception applies; rules and exceptions differ by account or plan. Review
IRS guidance on early distributions and discuss your circumstances with a qualified tax professional before relying on an early withdrawal.
What if retirement happens earlier than planned?
An earlier retirement can mean fewer earning years and more years of expenses. It may also create a period before expected benefits or healthcare coverage begin.
Review a second version of your estimates using an earlier retirement date. Identify which expenses could change, which resources are accessible, and which decisions can wait. Include part-time earnings only if that work is realistic for your health and circumstances.
If the figures show a gap, useful questions include whether you could adjust spending, change your timeline, or reconsider when income sources begin. Understanding the size and timing of a gap gives you something specific to address.
What should you have clear before choosing a date?
Before committing to retirement, aim to be able to explain:
- What your expected lifestyle costs, including occasional expenses.
- Which income sources will pay which bills, and when they begin.
- How much you expect to draw from savings.
- Where accessible funds will come from for an unexpected expense.
- How healthcare, taxes, inflation, and a longer retirement affect your estimates.
- What you could adjust if circumstances change.
Gather recent account statements, benefit estimates, pension information, insurance contracts, and spending records. Clear information makes conversations more productive and helps you recognize questions that need further attention.
Summerlin Benefits Consulting can help you understand retirement income and insurance options, including their costs and limitations. If you would like to discuss those questions, Request Your Complimentary Retirement Review.
This material provides general education and is not individualized investment, tax, or legal advice. Consult appropriately qualified professionals about your circumstances.
Frequently Asked Questions
Do I need to pay off my mortgage before retiring?
You do not necessarily need to pay off your mortgage before retiring. What matters is whether the payment and other housing costs fit your expected income while leaving adequate accessible resources. Compare the effect of keeping the mortgage with the effect of using savings to repay it, including any tax consequences.
Is my home equity the same as retirement income?
No. Home equity does not provide spendable income unless you take steps to access it. If you expect a home sale or another arrangement to support retirement, account for timing, costs, and your future housing needs before including that money in your estimates.
Does a retirement readiness review mean I need to buy an annuity?
No. Evaluating retirement readiness does not establish a need for an annuity. First understand your spending, existing income, available savings, and access needs. Any insurance recommendation requires a separate consideration of your circumstances and the specific contract's benefits, costs, and limitations.
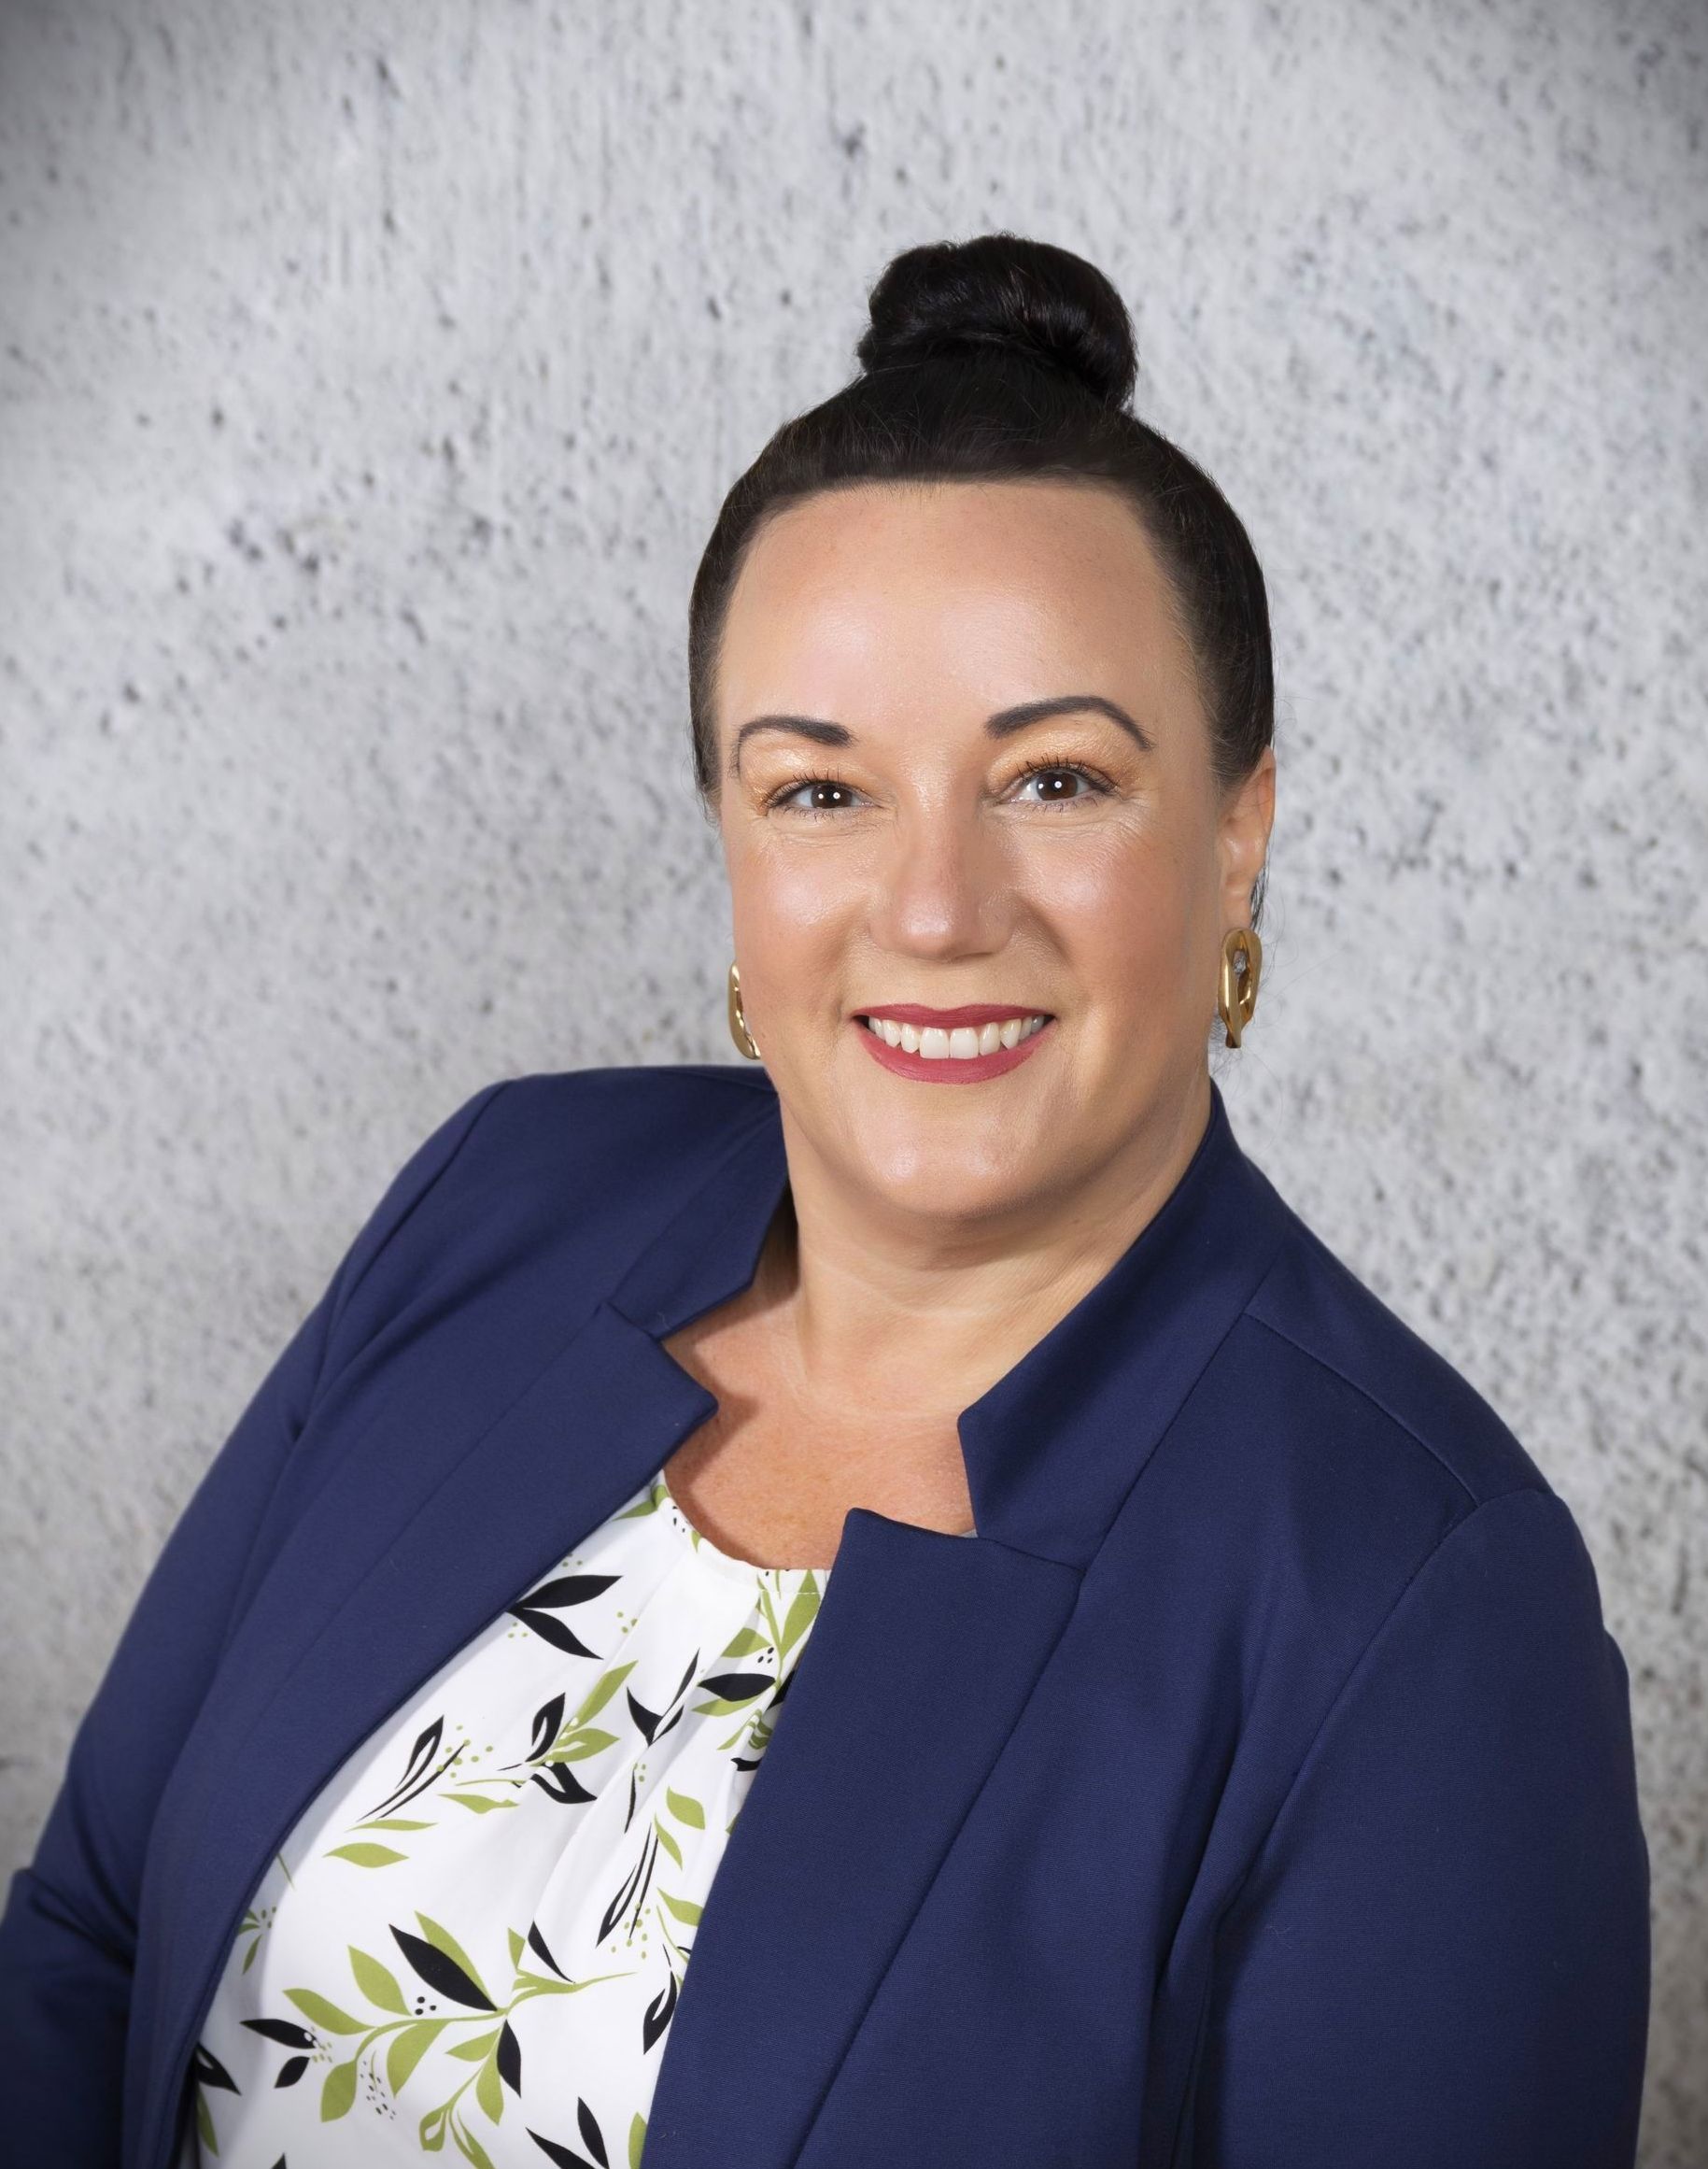
Meet Stacy Summerlin
29+ Years of Experience | Licensed in Florida & Georgia | Founder & President
For more than 29 years, Stacy Summerlin has helped individuals and families prepare for their financial needs with clarity, confidence, and peace of mind. As Founder and President of Summerlin Benefits Consulting, she specializes in helping pre-retirees and retirees protect what they've worked hard to build through an educational, personalized, safety-first approach to retirement.
Whether you're preparing to retire or already enjoying retirement, Stacy is committed to helping you understand your options and move forward with confidence.